Content Editor, Dunham | 2025 ThinkAdvisor Luminaries Award Winner | 2026 Wealthies Finalist, Thought Leader of the Year | Macroeconomics, markets, geopolitics & global trends
A currency war can develop when countries seek weaker exchange rates to improve trade competitiveness. Tariffs and currency depreciation can both raise import costs, while a weaker dollar may help U.S. exporters. This article examines whether trade tensions could encourage competitive depreciation and how the resulting shifts may affect inflation, commodity prices, foreign investment, and demand for U.S. financial assets.
Key Takeaways
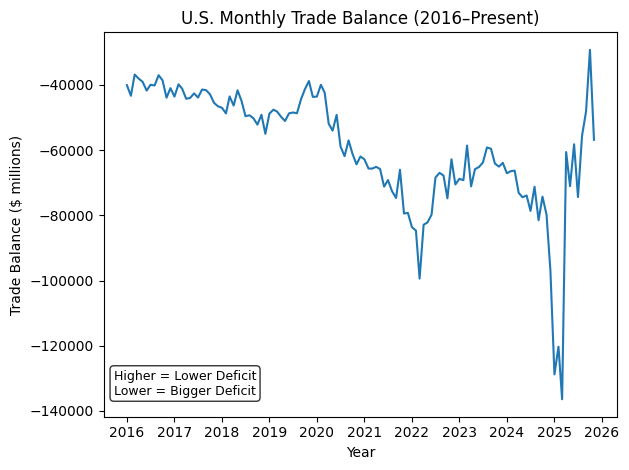
Trump’s tariffs have narrowed the U.S. trade deficit so far, but the deficit hasn’t disappeared — it rerouted through other countries like the EU as China redirected exports.
A weaker U.S. dollar can do what tariffs can’t: raise import prices and curb demand without the political cost of new tariffs.
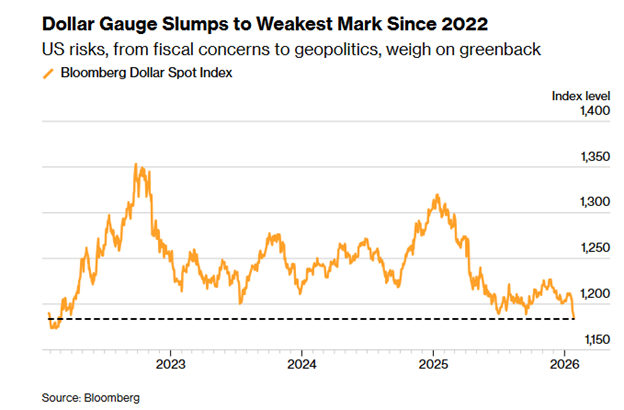
The dollar has fallen sharply since its January 2025 peak, and Trump has declined to defend it, calling it a “yo-yo.”
Currency depreciation is often a sign of policy exhaustion — a tool governments reach for once tariffs and fiscal stimulus hit political limits.
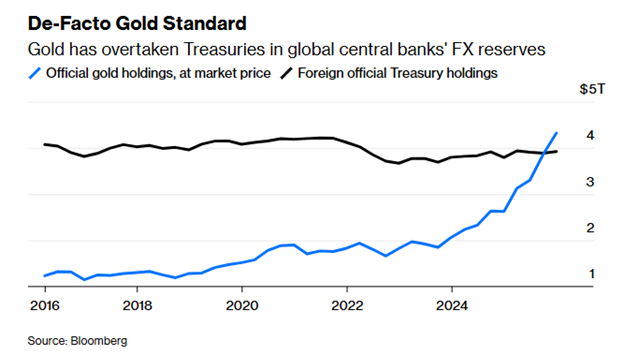
Central banks are already hedging against dollar risk: gold has overtaken U.S. Treasuries in global forex reserves for the first time in at least 20 years.
Since most global commodities are priced in dollars, a weaker dollar distorts price signals across markets, not just trade flows.
Listen to this blog here
10:55
Since late 2024, I’ve had a theory.
One grounded in history, economics, and geopolitics.
If President Trump were serious about trying to revitalize U.S. manufacturing, shrink the trade deficit, and boost exports, the strategy wouldn’t stop at tariffs.
Think about it this way. When the world’s largest buyer - and a chronic trade-deficit nation like the U.S. - signals it will buy less, exporters feel it immediately. That pressure is precisely why surplus countries came to the table. Like it or not, they depend on the U.S. consumer.
Whether tariffs were good policy or bad policy will be left to historians.
But tariffs are the. They are loud, politically polarizing, and easy to point to.
This is whereFrederic Bastiat’sinsight becomes useful.
The 19th-century French economist1warned that a bad economist stops atwhat is seen, while a good economist focuses onwhat is unseen– aka the delayed consequences and second-order effects that don’t show up right away.
Put simply, tariffs are what we see in upfront headlines. Whereas currency moves - and their impact on trade flows - are what we don’t.
And it’s the unseen effects that tend to matter most.
The First Act: Tariffs (So Far)
For all the controversy surrounding them, tariffs appear to have worked -so far.
That’s because tariffs are a form offinancial repression– aka the polite way governments tax households and businesses without calling it an outright tax.
For example: When tariffs raise the price of foreign goods, household purchasing power erodes, demand falls, imports decline, and the trade deficit narrows.
Many end the story right there. But there’s far more to it.
See, trade deficits don’t disappear - they justmove. They reroute through intermediaries. They re-emerge via different countries, different supply chains, and different invoices.
Astrongercurrency makes imports cheaper and exports more expensive.
Aweakercurrency does the opposite - it raises the cost of imports and makes exports more competitive abroad.
Most discussions only focus on the export side.And that’s a mistake.
Because the trade deficit doesn’t only narrow when exports rise. It narrows first becauseimports also need to fall.
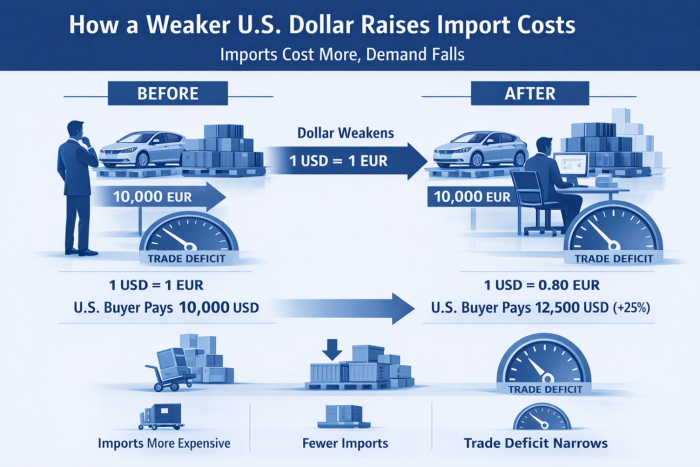
Here’s a simpleexample.
Say a foreign-made product sells for €10,000.
If the exchange rate is $1 = €1, a U.S. buyer pays $10,000.
Easy, right?
But let’s say the dollar weakens to $1 = €0.80.
When the dollar loses 20% of its buying power, you now need 25% more dollars to buy the same foreign good.
That same product now costs $12,500.
Figure 4: Dunham, 2026
Nothing changed overseas. The product didn’t improve. The seller didn’t raise prices.
But for the U.S. buyer, the cost jumped25%purely because of the exchange rate.
That’sthe first-order effectof a weaker dollar.
Aka it raises import prices, curbs demand, and reduces imports - narrowing the trade deficit without the political blowback of further tariffs. (But inflation, of course, becomes the trade-off).
This is why currency depreciation can succeed where tariffs struggle. Tariffs make loud headlines – whereas currency moves are more subtle.
Yet for trade flows, the end result can look strikingly similar.
Why Not Boost Exports Instead of Curbing Imports?
You may be wondering,“To close the deficit, why not just boost exports more?”
That would be the best-case scenario.
But it poses a problem. . .
For U.S. exports to rise meaningfully, foreigners need to increase their own domestic demand.
That means Europeans consuming more.
Chinese households consuming more.
And emerging markets expanding their middle classes at a rapid pace.
That’s a tall order.
Many of those economies are aging, highly indebted, politically constrained - or all three.
They may not be able - or willing - to become thedemand enginethe U.S. needs them to be.
So, the U.S. can make its goods cheaper through weakening the dollar. But it cannot force the world to buy more. Not at scale. Not quickly.
Putting it another way: sure, boosting exports from a weaker dollar is great. But that’s a side effect. The real goal is toreduce the import side.
Final thoughts: Why Currency Wars Signal Policy Exhaustion
And here’s the part few talk about.
Currency wars are rarely signs of strength. More often, they’re signs of policy exhaustion.
A government leans on the currency when other tools start to fail - when tariffs hit political limits, fiscal policy becomes harder to justify, and growth still needs to be supported without calling it stimulus.
Currency becomes thepath of least resistance. Outcomes change, but no one has to take a visible “vote” on it.
But I can’t stress this part enough. Sure, that can work –but up to a point.
If the U.S. leanstooheavily on debasement, it risks a more serious consequence.
I’m talking about a gradual erosion in the world’s willingness to absorb U.S. assets at any price.
This wouldn’t happen overnight. Not through a dramatic “dollar collapse” headline.
Think of the dollar as“too big to fail.”No one wants it to collapse, as it would drag down the entire global economy.
It would be more subtle.
Foreign buyers begin to demand higher yields. Marginal reserves get diversified. Duration shortens. Capital still flows - but it becomes more conditional, more selective, and more expensive.
This isn’t surprising. Wouldn’t you do the same if the paper currency you were paid in was going to weaken?
So yes, while a weaker dollar will likely help rebalance the U.S. economy – it likely won’t happen on a political timetable.
It’ll unfold overyears- not quarters. Supply chains change slowly. Investment decisions lag. Consumer behavior is the last to change. In the meantime, the economy absorbs higher prices, tighter margins, and rising political tension as affordability becomes a sticking point.
One final point is critical. The U.S. dollar doesn’t just influence trade - it anchors the global pricing system.
Most major commodities, from oil to copper to agricultural goods, are priced in dollars.
When the dollar weakens, prices often rise across asset classes, even if underlying demand hasn’t changed.
This creates a dangerous signal problem. . .
For example, is copper rallying because global demand is accelerating and justifies new supply?
Or is it simply the result of a weaker dollar pushing nominal prices higher?
When currencies distort prices, they distort decision-making - buying habits, investments, production plans, and all can become less reliable and more volatile.
In that sense, dollar debasement doesn’t just export inflation to dollar holders - it clouds the information embedded in prices themselves.
Final Thoughts
All this brings us back toFredricBastiat.
Thebenefitsof a weaker dollar are seen immediately - improved trade data, better export competitiveness, higher nominal GDP, and higher asset prices.
Thecosts(like inflation, volatile commodity prices, bubbles) areunseen– delayed, dispersed, and harder to measure. But no less real.
And once they arrive, they tend to linger.
So, keep this in mind as the next wave of the trade war ramps up.
Because currencies affecteverything.
Frequently Asked Questions About a Weaker U.S. Dollar
Is Trump trying to weaken the dollar? Trump's January 2026 comments show he is comfortable with a drop, but words alone do not prove a planned push to weaken it. Showing real intent takes official action or direct policy steps. For investors, what matters most is how talk sways market views. That plays out alongside interest rates, economic growth, and global demand for dollar assets.
How does a weaker dollar affect the trade deficit? It can help shrink the gap over time, but it often widens the deficit first. A softer dollar makes American exports cheaper abroad and imports pricier at home. That helps U.S. goods compete, yet supply contracts take time to adjust. When essential imports are tough to replace quickly, the higher price tag can temporarily make the deficit worse.
How do tariffs and currency depreciation differ? Tariffs are targeted taxes on specific goods, while a lower dollar changes prices across all imports and exports. Both raise costs for imported products, though companies might absorb some hits or change price tags. Their full impact depends on foreign retaliation, buyer demand, and supply chains. That leaves the final outcome for trade balances far from certain.
What are the risks of a weaker dollar? A falling dollar raises import costs, cuts what Americans can buy abroad, and lowers foreign returns on U.S. assets. It can also swing raw material costs and lending conditions. Investors should not expect every asset to move the same way. Instead, look closely at currency hedges, reliance on imported parts, and how sensitive each holding is to inflation.
This communication is general in nature and provided for educational and informational purposes only. It should not be considered or relied upon as legal, tax or investment advice or an investment recommendation, or as a substitute for legal or tax counsel. Any investment products or services named herein are for illustrative purposes only, and should not be considered an offer to buy or sell, or an investment recommendation for, any specific security, strategy or investment product or service. Always consult a qualified professional or your own independent financial professional for personalized advice or investment recommendations tailored to your specific goals, individual situation, and risk tolerance.
Information contained in the materials included is believed to be from reliable sources, but no representations or guarantees are made as to the accuracy or completeness of information.
Dunham & Associates Investment Counsel, Inc. is a Registered Investment Adviser and Broker/Dealer. Member FINRA/SIPC. Advisory services and securities offered through Dunham & Associates Investment Counsel, Inc.