Content Editor, Dunham | 2025 ThinkAdvisor Luminaries Award Winner | 2026 Wealthies Finalist, Thought Leader of the Year | Macroeconomics, markets, geopolitics & global trends
The Keynesian Beauty Contest is an investing analogy developed by John Maynard Keynes to explain how expectations about other investors influence market prices. Investors anticipate what the crowd will favor and how others interpret prevailing sentiment. The framework gives financial advisors a useful way to discuss speculation, market narratives, and the role of crowd psychology in clients’ own investment decisions.
Key Takeaways
The Keynesian Beauty Contest illustrates how markets are driven less by fundamentals and more by expectations about others’ expectations.
Crowd psychology, bounded rationality, and fear-of-missing-out behavior often shape short-term price movements.
The Greater Fool Theory helps explain why trends can persist far beyond intrinsic value.
Advisors can use this framework to help clients understand bubbles, panics, and narrative-driven markets.
Fundamentals matter over the long run, but psychology often moves prices first.
A stock can look expensive and keep climbing. Another can look cheap and stay overlooked.
Why? Investors aren’t just evaluating businesses. They’re also anticipating how other investors will respond.
That’s where the Keynesian Beauty Contest earns a place in an advisor’s mental toolbox.
What Is the Keynesian Beauty Contest?
We all like to think we are rational actors who use logic to make our decisions.
We look at a balance sheet. Calculate intrinsic value. And buy when the price is lower than that value, believing it will always revert to that baseline.
Simple, right?
Except - unfortunately - that’s not how markets usually work.
John Maynard Keynes - known as the father of modern macroeconomics and a brilliant thinker - hit the nail on the head nearly a century ago with his concept of the “Beauty Contest”.
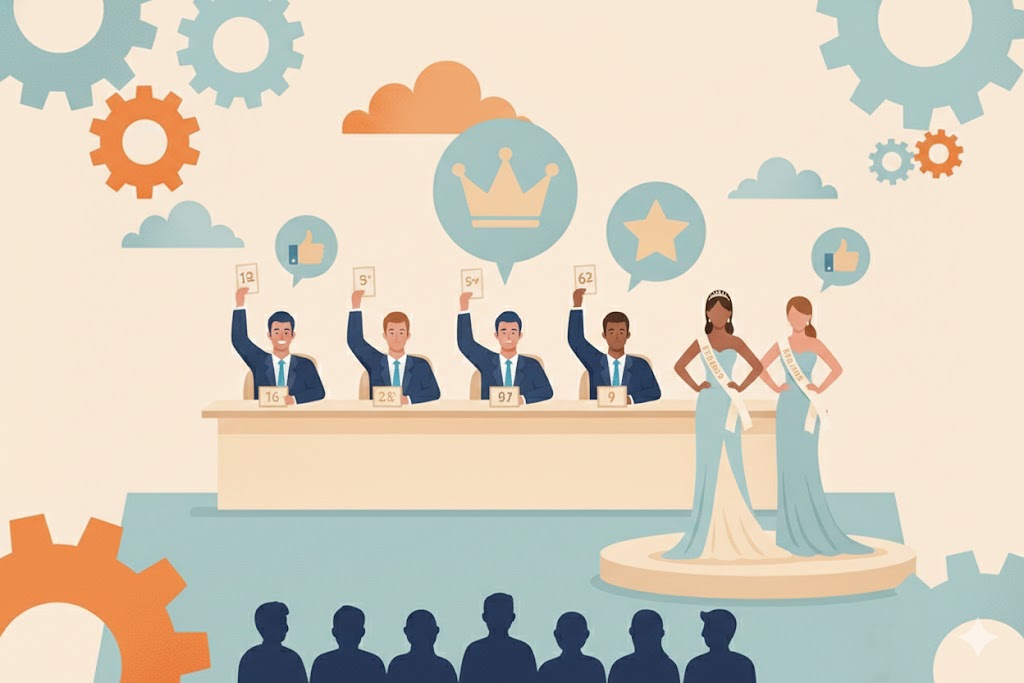
Here's the gist: Imagine a newspaper runs a beauty contest where you have to pick the six faces that are the "most beautiful" from a hundred photographs.
But here’s the angle - the prize is awarded to the competitor whose choice most nearly corresponds to the average preferences of the competitors as a whole.
Meaning if you pick the faces you truly find the best looking, but nobody else does - you lose.
Thus, to win, you have to disconnect from your own taste and instead must ask, “Which face do I believe the others will think is the prettiest?”
This type of 4D Chess means you must think several moves ahead of the crowd.
First-Level Thinking:“Which faces do I find the prettiest?” (This is choosing based on your own intrinsic value.)
Second-Level Thinking:"If everyone is playing this game, then they’re all thinking the same thing. So, what does the average opinion expect the average opinion to be?" (This is anticipating the anticipation of others.)
Now, think about investing. You're not paid for finding the stock you believe offers the best value. You're paid for finding the stock that the most people will believe has value tomorrow.
Level
Beauty Contest Question
Investing Equivalent
Your own judgment
Which faces do I prefer?
What do I think this business is worth?
Others’ preferences
Which faces will other contestants choose?
Which investments will other investors favor?
Others’ expectations
Which faces will contestants expect everyone else to choose?
What does the crowd expect other investors to favor?
How Keynes Understood Financial Behavior
This is what made Keynes different.
He wasn’t just describing a game - he was diagnosing how financial markets actually work.
Said another way- he realized that markets aren’t cold calculators. They’re crowds - and crowds trade on emotions, biases, and expectations.
Keynes understood - long before behavioral theorists like Kahneman or Thaler - that humans suffer from what we now call bounded rationality.
Put simply, people don’t have infinite time, perfect information, or endless analytical horsepower. So instead of digging for intrinsic value, they look around, read the room, and follow the herd.
We seek a decision that is good enough rather than the best possible option
Thus, in markets, that herd behavior isn’t a side effect. It's the mechanism.
The Greater Fool Theory
And this brings us to the Beauty Contest’s wild cousin - the Greater Fool Theory.
If the Beauty Contest explains why people chase trends, the Greater Fool Theory explains how far they’ll go.
Meaning, you’re not buying because you believe something is intrinsically worth it - you’re just buying because you think there’s a "greater fool" who will pay more for it.
Buy high. Hope to sell higher. And pray you’re not the last one standing when the music stops.
Together, the Beauty Contest and Greater Fool Theory help explain nearly every mania you see today - meme stocks, crypto cycles, AI melt-ups, housing frenzies, even the 2020–2021 everything-bubble dynamic.
None of it requires fundamentals. It requires expectations - specifically, expectations about everyone else’s expectations.
Why This Matters for Advisors
Sometimes (more often than not), people don’t chase real value – they chase validation.
They want to be where “everyone else is.” They want confirmation - not calculation. The Beauty Contest explains why clients' FOMO (fear of missing out) into bubbles, why they panic during corrections, and why they always seem to chase the narrative of the moment.
This context andframework give advisors a way to talk about those behaviors without shaming the client or lecturing them about valuations.
Keynes understood the uncomfortable truth – that markets often reward you for understanding the crowd more than understanding the company.
Fundamentals matter - eventually - but psychology usually moves first.
So How Did Keynes “Win” the Game?
After struggling early in his investment career, Keynes stopped trying to outguess the crowd at every whim.
He realized that short-term price movements are mostly a guessing contest, layered with flawed assumptions about what other flawed people might do.
Thus, instead of timing the Beauty Contest, he focused on value investing - buying assets beaten down by fear and selling when greed returned.
He realized you can’t win a game where everyone keeps guessing everyone else’s guesses.
But you can help your odds by understanding how the psychology around it moves.
The Takeaway
The Keynesian Beauty Contest belongs in every advisor’s mental toolbox because it explains so much of what drives modern markets - bubbles, manias, panics, sudden re-ratings, changing narratives, and the constant tug-of-war between valuations and expectations.
The point is, you’re not just investing in companies. You’re investing in what other people believe about other people’s beliefs about those companies.
And by helping clients understand that, things can start making a lot more sense.
Frequently Asked Questions About the Keynesian Beauty Contest
What is the Keynesian Beauty Contest? The Keynesian Beauty Contest is an analogy John Maynard Keynes introduced in 1936 to explain how investors anticipate other investors’ expectations. He described a newspaper competition where contestants chose faces they expected others to favor. Applied to investing, the question becomes: “What will other buyers find attractive, and how much of that expectation is already reflected in today’s price?”
What is an example of the Keynesian Beauty Contest in investing? Imagine an investor buying an AI stock because they expect its popularity to attract more buyers. They also believe other investors anticipate that same buying wave. This hypothetical illustrates the beauty contest’s layers of expectations. To examine the decision, ask: “What would justify this purchase if enthusiasm cooled?” That question helps separate assumptions about future demand from the investment’s underlying prospects.
How does the Keynesian Beauty Contest differ from the Greater Fool Theory? The Keynesian Beauty Contest describes investors anticipating the crowd’s expectations. The Greater Fool Theory involves buying an overvalued asset while expecting someone else to pay more. The two overlap when anticipated enthusiasm becomes the reason for accepting a stretched valuation. A useful question is: “Does this investment have a credible return case if another buyer never offers a higher price?”
How can crowd psychology cause stock market bubbles? Stock market bubbles can grow through a feedback loop: rising prices attract attention, enthusiasm encourages buying, and additional demand pushes prices higher. Consider a hypothetical investor who treats recent gains as evidence that more gains will follow. Before buying, they could ask what earnings, growth, or future demand would justify the price—and what happens if those expectations prove too optimistic.
This communication is general in nature and provided for educational and informational purposes only. It should not be considered or relied upon as legal, tax or investment advice or an investment recommendation, or as a substitute for legal or tax counsel. Any investment products or services named herein are for illustrative purposes only, and should not be considered an offer to buy or sell, or an investment recommendation for, any specific security, strategy or investment product or service. Always consult a qualified professional or your own independent financial professional for personalized advice or investment recommendations tailored to your specific goals, individual situation, and risk tolerance.
Information contained in the materials included is believed to be from reliable sources, but no representations or guarantees are made as to the accuracy or completeness of information.
Dunham & Associates Investment Counsel, Inc. is a Registered Investment Adviser and Broker/Dealer. Member FINRA/SIPC. Advisory services and securities offered through Dunham & Associates Investment Counsel, Inc