Content Editor, Dunham | 2025 ThinkAdvisor Luminary Award Winner | 2026 Wealthies Finalist — Thought Leader of the Year | Macroeconomics, markets, geopolitics & global trends
Listen to this blog here
10:36
OPEC+ struggles to defend oil prices because every member has an individual incentive to pump more while hoping others cut, a dynamic economists call the prisoner's dilemma. Saudi Arabia has repeatedly cut its own output to prop up prices, only to watch rivals like Russia, Iran, and non-OPEC producers capture the market share it gave up, which helps explain why oil has kept drifting lower despite years of announced cuts.
Update | July 2026: Since this article was first published, OPEC+ fractures have intensified. Angola left OPEC, the UAE announced its exit, and OPEC+ began unwinding production cuts. The core problem remains the same: each producer benefits from selling more oil while hoping others restrain supply, creating a classic prisoner’s dilemma.
Key Takeaways
OPEC+ faces a classic prisoner’s dilemma: every producer benefits if the group cuts supply, but each member has an incentive to pump more while others take the hit.
Saudi Arabia’s production cuts may support oil prices in theory, but they also sacrifice market share to rivals like Russia, Iran, the U.S., Brazil, Canada, and other non-OPEC producers.
OPEC+ cooperation is weakening as quota disputes, Angola’s exit, the UAE’s announced departure, and rising output from some producers expose deeper fractures inside the cartel.
Oil prices have continued to underwhelm despite repeated OPEC+ cuts because supply discipline is difficult to enforce across countries with different budgets, politics, and production goals.
If price defense keeps failing, Saudi Arabia may eventually shift back toward market share defense by increasing production and pressuring higher-cost producers.
Why Are Oil Prices Falling Despite OPEC+ Cuts?
Over the past year, oil has taken a beating.
Brent crude, the global benchmark for about two-thirds of internationally traded oil, peaked at $128 per barrel in March 2022. By November 30, 2023, it had slumped to around $81 - a .
As of February 2026, Brent crude is now $67 per barrel. Down roughly 50% since its March 2022 cyclical peak.
But here’s the thing: I’m not surprised. . .
Despite headline after headline about OPEC+ production cuts - led by Saudi Arabia - oil prices have kept drifting lower. The cuts haven’t worked. Why?
Because every time Saudi Arabia cuts output to prop up prices, other producers ramp up and cash in. They're benefiting while the Saudis take the hit. And this isn’t a new phenomenon - it's a recurring pattern that can be explained through game theory.
What Is the Prisoner’s Dilemma?
So, what exactly is the prisoner’s dilemma?
Put simply, it’s a game theory concept coined by mathematicians Merrill Flood and Melvin Dresher during the Cold War in 1950 to help make strategic decisions.
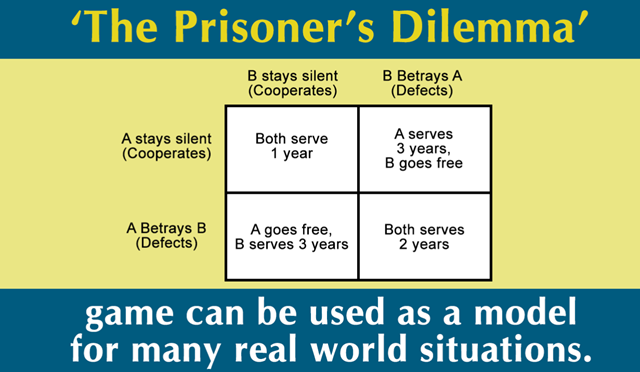
Imagine two suspects are arrested and placed in separate rooms. Each has two choices:
Stay silent (cooperate)
Confess (betray the other)
If both stay silent, they get light sentences. If one confesses and the other stays silent, the betrayer walks free and the silent one gets a heavy sentence. But if both confess, they both get medium sentences.
The catch? Each person is better off betraying—no matter what the other does. So both usually betray... and both lose.
This is exactly what’s playing out in the oil market.
Figure 1: Psychologenie
Thus, the prisoner’s dilemma illustrates the challenges of cooperating when individuals or groups face conflicting interests.
Sometimes, choosing self-interest might not be of any value to you if others think only of their own gain.
For instance, if you think of the best interest of the group, but the other members of the group think of only their self-interests, you’ll end up bearing all the loss (just like the suspect who stays silent while the other blames him).
This prisoner’s dilemma gives us a great framework when looking at Saudi Arabia and OPEC oil cuts.
Because they’re looking like the real losers here. . .
How Does the Prisoner’s Dilemma Explain OPEC+?
The biggest problem with the OPEC oil cuts is that each time they limit output (in an attempt to raise oil prices), other producers benefit – such as the U.S., Brazil, and Canada.
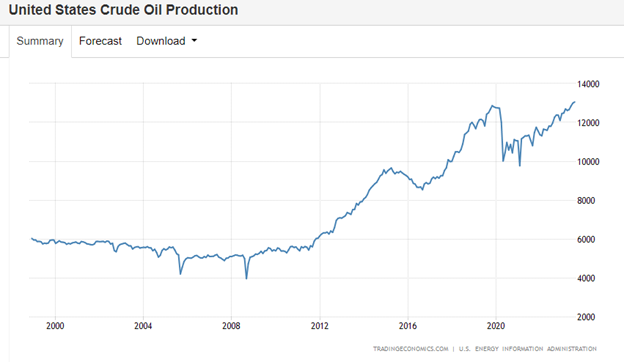
For instance, U.S. oil production just hit a record high 13.05 million barrels per day in August 2023.
Figure 2: TradingEconomics, 2024
This is a thorn in the side of OPEC as they’re losing market share (reducing output) to try and keep prices higher while others – like the U.S. - come in and soak it up.
But let’s discuss OPEC itself here. . .
I believe there are two fundamental issues within OPEC – and even OPEC+ (aka including Russian and the Caucasus oil producers).
Oil revenues make up most of the income for several oil-producing countries. Thus, their government budgets and dollar reserves depend on oil output.
Most of these countries have nationalized oil producers. Hence the state can choose oil output targets arbitrarily (whereas, for example, in the U.S. and Canada there is no mandated control of oil output).
So, in this context of OPEC, member countries face a dilemma when deciding on oil production levels.
Each country has an incentive to maximize its oil output to increase its revenue and gain a larger market share. And it often leads to cheating.
Why Do OPEC+ Members Cheat on Production Cuts?
OPEC tries to address this dilemma through cooperation and collective decision-making.
The organization – under the heel of Saudi Arabia – sets production quotas for member countries, aiming to stabilize oil prices and maintain a balanced market. By limiting production, OPEC attempts to manage supply levels and support higher oil prices (a win-win).
However, the prisoner’s dilemma dynamics come into play when individual countries consider their own self-interests. . .
For instance, if one country decides to exceed its production quota (let’s say Russia or Iran) and increase output, it can benefit by capturing a larger market share, potentially earning more revenue at the group’s expense.
But if they all ‘cheat’ (because they don’t know if others are abiding by production cuts) – it can flood the market with oil (a lose-lose).
This creates tension within OPEC, as each member tries to strike a balance between maximizing their own gains and maintaining stability in the oil market.
And this “cheating” aspect happens much more often than many realize.
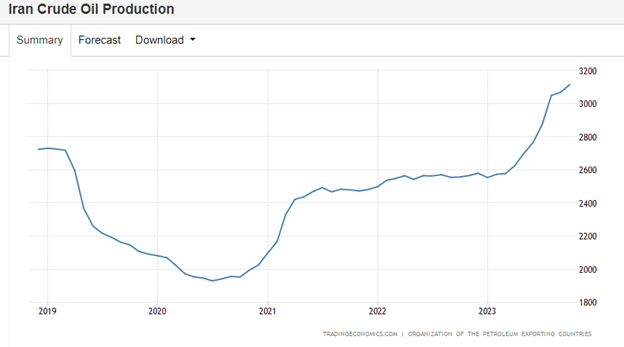
To put this into perspective, look at Iran's oil output (which was a founding member of OPEC) over the last few months. It’s risen roughly 600,000 barrels per day since this time last year – an over 20% increase.
Figure 3: TradingEconomics, 2024
It's important to note that Iran, Libya, and Venezuela are exempt from OPEC production quotas (meaning they don’t have set production limits).
Why Saudi Arabia Loses Market Share When OPEC+ Cuts Production
Still, this is an awkward situation4 for Saudi Arabia – the main entity in OPEC – as they’re cutting while Iran (a geopolitical rival) increases output.
Or to put it another way – Iran is gaining at Saudi Arabia’s expense.
Saudi Arabia and OPEC often face challenges in enforcing production quotas and preventing free-riding behavior, where some countries exceed their limits while others adhere to them (win-lose).
And we’re already seeing the tension and resentment build in OPEC. . .
For instance, a few days ago, Saudi Arabia announced5 that they were delaying the OPEC+ meeting because it was “dissatisfied” with other members’ output levels – specifically the African producers and Iran.
Saudi Arabia is having difficulty with other OPEC+ countries that don’t exactly want to cut oil output since they depend on these revenues. Instead, these countries want to have their quotas increased (allowing more output).
In fact, after the meeting today, Angola – the second largest African oil producer in the cartel – said6 that it outright rejected the OPEC quota and will pump more oil than the quota dictates – which is a rare challenge to the Saudis.
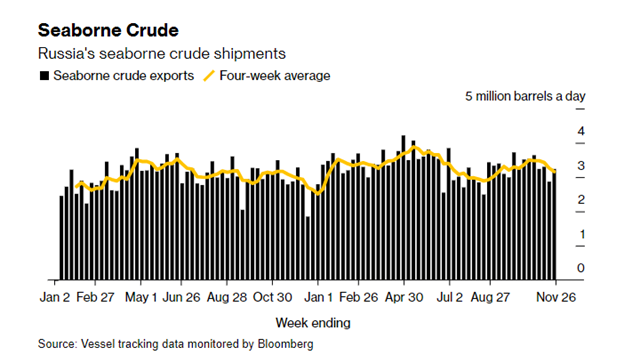
Meanwhile, Russian crude oil exports have been rising when they should’ve been declining from “promised” 2023 cuts.
In fact – according to Bloomberg7 – Russian crude flows to international markets through seaborne shipments have been rising since August – and remain elevated at more than 500,000 barrels a day higher than they were at the end of 2022.
Figure 4: Bloomberg, 2023
Russia appears to be losing its appetite to help prop up oil prices by cutting supply alongside OPEC+ ally Saudi Arabia.
Exports of Russian crude have steadily risen since August lows, even as the two countries reaffirmed their close “cooperation” in the oil market.
But looking at it from the prisoner’s dilemma angle – this makes sense.
The Russians can let Saudi Arabia and OPEC cut oil production further – thus pushing prices higher in the paper markets - while they reap the reward (higher margins).
Keep in mind that Russia is fighting a war in Ukraine and dealing with a weak domestic economy - forcing them to depend on oil revenues very heavily (their largest export is petroleum products).
And this is just Russia I'm talking about. . .
There are currently 13 OPEC member countries, and 23 if we include OPEC+.
All these competing actors trying to fulfill their own best interests are becoming the biggest problem for Saudi Arabia.
Because with each oil cut OPEC tries to do, it’s subsidizing U.S., Russian, Canadian, African, and Brazilian oil production (which have all risen steadily over the last two years) at their own expense.
Could Saudi Arabia Flood the Oil Market Again?
Saudi Arabia is already expected to run a $21 billion deficit in 2023 (over 1.9% of GDP). How long will they continue doing so while others benefit?
No wonder there’s tension building within OPEC.
These countries don’t want to lose oil market share and the revenues they depend on for state budgets all to prop up other producers.
And if history means anything here – I expect further ‘cheating’ by OPEC members and further infighting.
Thus, the prisoner’s dilemma highlights the complexities faced by OPEC in maintaining cooperation and managing oil production.
It underscores the need for trust, effective communication, and a collective commitment to shared goals to avoid a “race to the bottom” scenario where everyone suffers from declining oil prices.
But as we’ve seen, these three things don’t really exist in the real world. As each country has its interests and is always looking for an advantage.
Eventually, I believe Saudi Arabia may flood the market with oil to try and price out marginal producers and regain market share.
We’ve seen it happen before. . .
FAQ
What is the prisoner’s dilemma, and how does it apply to OPEC+? The prisoner’s dilemma is a game-theory concept in which each participant has an incentive to pursue its own short-term interest even though cooperation could produce a better collective outcome. For OPEC+, coordinated production limits can support oil prices. However, an individual producer may benefit by exceeding its quota while other members restrain output. That tension can make quota compliance difficult, especially when countries need more oil revenue or seek greater market share.
Why do OPEC+ members exceed their production quotas? Many OPEC+ members depend heavily on oil revenue to support government budgets, public spending, and national oil companies. Higher production can increase revenue and market share, particularly when oil prices are high or fiscal needs are acute. Production levels can also differ from quotas because of technical constraints, domestic policy, conflict, sanctions, or efforts to restore output after disruptions. Iran, Libya, and Venezuela are currently exempt from OPEC+ production cuts.
Has OPEC+ actually unwound its production cuts? Yes. OPEC+ completed the phased rollback of a 1.65 million-barrel-per-day voluntary production cut in September 2026. The increase involved Saudi Arabia, Russia, Iraq, Kuwait, Algeria, Kazakhstan, and Oman. The practical effect on global supply has been affected by disruptions linked to the Iran and Ukraine wars, so higher quotas do not always translate into immediate increases in physical oil exports.
Could Saudi Arabia abandon price defense and focus on market share? It is possible, but not certain. Saudi Arabia has previously increased output during periods when it sought to defend market share, including during the 2014–2015 period of rapid U.S. shale growth. In 2026, Saudi Aramco cut official selling prices for Asian buyers after the Iran war, which some analysts viewed as a sign of market-share competition. The broader strategy will depend on global oil demand, supply disruptions, OPEC+ cooperation, spare capacity, and Saudi fiscal priorities.
This communication is general in nature and provided for educational and informational purposes only. It should not be considered or relied upon as legal, tax, or investment advice or an investment recommendation, or as a substitute for legal counsel. Any investment products or services named herein are for illustrative purposes only and should not be considered an offer to buy or sell, or an investment recommendation for, any specific security, strategy, or investment product or service. Always consult a qualified professional or your own independent financial professional for personalized advice or investment recommendations tailored to your specific goals, individual situation, and risk tolerance.
Information contained in the materials included is believed to be from reliable sources, but no representations or guarantees are made as to the accuracy or completeness of information.
Dunham & Associates Investment Counsel, Inc. is a Registered Investment Adviser and Broker/Dealer. Member FINRA/SIPC. Advisory services and securities offered through Dunham & Associates Investment Counsel, Inc.