Content Editor, Dunham | 2025 ThinkAdvisor Luminary Award Winner | 2026 Wealthies Finalist — Thought Leader of the Year | Macroeconomics, markets, geopolitics & global trends
FINRA raised its gift limit under Rule 3220 from $100 to $300 per person, per year, the first increase since the rule was set in 1992. The SEC approved the change on February 12, 2026, and it took effect March 30, 2026, giving advisors more room to give meaningful gifts to centers of influence, referral partners, and vendors, while keeping firm-wide aggregation, supervision, and valuation requirements intact.
Listen to this blog here
8:06
Well, it's about time.
FINRAfinally raised the annual gift limit from $100 to $300 per person, per year - the first increase since 1992. The SEC approved it February 12, 2026. It took effect March 30.
The old cap had become comical. Now, advisors and firms actually have a little more room to operate like it's not 1992 - when gas was about a dollar a gallon and a movie ticket cost roughly $4.
Here’s everything you need to know.
What Changed Under FINRA Rule 3220
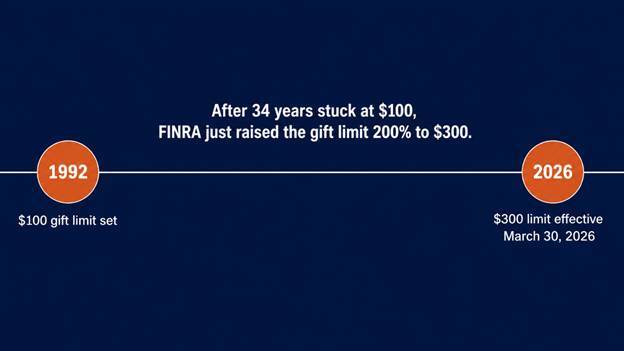
For over three decades - the gift cap under FINRA Rule 3220 sat fixed at $100 per person over any given year. This means if you gave a COI a holiday gift and a birthday gift in the same year, both had to cost less than $100 combined (excluding taxes and shipping costs).
Figure 1: Dunham, May 2026
By 2026, that number was badly out of step with reality. Three decades of inflation had made it nearly impossible to give a professional, meaningful gift within the limit - and everyone in the industry knew it.
FINRA cited inflation since 1992 as a key rationale for increasing the limit to $300. The proposal started at $250, got bumped to $300 after industry feedback (some commenters pushed for $500).
Here's what the updated rule means in practice:
The new limit: $300 per person, per year - for gifts tied to an existing or potential business relationship.
Who it covers: Employees of institutional customers, vendors, and counterparties - wholesalers, CPA firm contacts, referring attorneys, plan administrators in connection with business relationships.
Who it does not cover: While FINRA Rule 3220 does not apply to retail clients, your firm policy may still require these gifts to be reported and subject to the gift limits.
Note that before adjusting any gift practices, check your firm's WSPs. Internal policies vary - some firms cap gifts well below the FINRA floor, and the rule change doesn't override them.
Beware: The Rule Still Has Teeth
Keep in mind that a higher limit doesn't mean a looser standard.
Here are a few things every advisor needs to know before spending up to the new cap.
Figure 2: FINRA, Dunham, May 2026
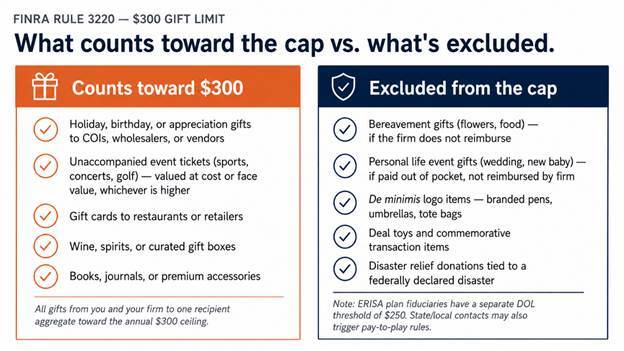
Aggregation is firm-wide. All gifts from you and your firm to a single recipient count together toward the $300 annual ceiling. A $150 gift from you and a $175 gift from your branch manager to the same COI puts you over the line.
Compliance still reviews it - not you. Gifts are subject to firm supervision and typically require review under firm policies.
Tickets are valued at the higher of cost or face value. Bought StubHub seats for $400 and handed them off without attending? Well, those are gifts - valued at face or what you paid, whichever is higher.
Attend the event and it's entertainment - not a gift. The accompanied-versus-unaccompanied distinction is one of the most common compliance errors in FINRA exams. Know which bucket you're in before you buy the tickets.
ERISA recipients have a lower threshold. ERISA guidance treats gifts differently and may impose stricter fiduciary standards; practitioners often reference a ~$250 non-enforcement threshold, but it will depend on the facts and circumstances.
What falls outside the cap entirely:
Bereavement gifts – such as flowers, food - if the firm doesn't reimburse them.
Personal life event gifts (wedding, new baby, etc) - but only if you pay out of pocket and the firm doesn't cover it.
De minimis (Latin for minimal things) logo items - like branded pens, umbrellas, tote bags.
Disaster relief donations tied to federally declared disasters.
Graduation Season: A Natural Opening
Even though it’s a few months away from the real gift-giving season (December), there are still big things in May.
For instance, graduation invitations are hitting mailboxes. If a COI, referral partner, or wholesaler contact has a child crossing a stage this spring, a thoughtful gift is a real relationship moment - the kind that gets remembered.
Under the old $100 cap, that gesture felt tight. But under $300, you have room to do something that actually means something.
A few ideas that feel like they came from someone who thought about it:
A quality book on leadership, entrepreneurship, or wealth ($25–$50)
A premium leather portfolio or journal ($75–$125)
A bottle of wine or whiskey from a local producer ($80–$150)
A curated gift box - coffee, chocolates, charcuterie from an artisan brand ($100–$200)
A restaurant gift card to somewhere worth going ($100–$200)
A round of golf at a course they've mentioned ($150–$275)
Best of all, most of these are quality gifts and leave you with money left over for other important dates later in the year.
What Advisors and Firms Should Do Now
If your firm has not already updated its supervisory framework, now may be the time.
The March 30, 2026 effective date has already passed. Firms can (if you haven't) review written supervisory procedures, gift logs, approval processes, aggregation methodology, and training materials to make sure they reflect the amended rule.
Advisors should also avoid treating the higher cap as a green light to get casual. The more useful way to think about the rule is that FINRA has raised the ceiling on the limit, but it has also made the compliance expectations more explicit.
Put simply, it means better flexibility - but not less responsibility.
For many firms, this is also a good time to re-check how gifts are categorized internally, especially where there is confusion around retail clients, business entertainment, event tickets, or reimbursed personal gifts.
Final Take
The rule is already in effect. Thus, if your firm hasn't updated its written supervisory procedures, gift-tracking process, or compliance review workflow – that’s worth doing.
But beyond compliance - think about this as a new relationship opportunity. Thirty-plus years of a $100 ceiling made thoughtful professional gifting nearly impossible to execute within the rules. That constraint is now gone.
COI relationships, referral networks, tech vendors, money managers, and wholesaler partnerships are built on consistent gestures over time. Sure, a $300 annual budget isn't lavish. But it's enough to matter now.
Now we just need to be hopeful they don’t wait another 30+ years.
Frequently Asked Questions About the Updated FINRA Gift Limit
What is the new FINRA gift limit for financial advisors? The FINRA gift limit under Rule 3220 is now $300 per person, per year, up from $100. The SEC approved the increase on February 12, 2026, and it took effect March 30, 2026. It's the first change to the limit since it was set back in 1992.
Who does the FINRA $300 gift limit apply to? It applies to gifts tied to the business of the recipient's employer, like gifts to employees of institutional customers, vendors, wholesalers, referring attorneys, or plan administrators. It doesn't cover gifts to individual retail customers or gifts from a firm to its own associated persons, though firms can still set stricter internal limits for retail clients.
Do gifts from multiple people at the same firm count toward the $300 limit? Yes. FINRA requires firms to aggregate every gift given by the firm and each of its associated persons to one recipient over the year. So if an advisor gives $150 and a colleague at the same firm gives $175 to that same person, the combined total tops $300 even though neither gift alone crossed the line.
Are event tickets counted as gifts under the FINRA rule? It depends on whether the giver attends. If an advisor buys tickets and hands them off without going, they're valued at the higher of cost or face value and count toward the $300 cap. If the advisor attends the event with the recipient, it's treated as business entertainment instead, which trips up a lot of compliance reviews.
What gifts are exempt from the FINRA $300 limit? A few categories fall outside the cap entirely: bereavement gifts like flowers or food, as long as the firm doesn't reimburse them, personal life-event gifts such as weddings or a new baby paid out of pocket, de minimis promotional items like branded pens or tote bags, and donations tied to federally declared disasters.
Disclosures
This communication is general in nature and provided for educational and informational purposes only. It should not be considered or relied upon as legal, tax or investment advice or an investment recommendation, or as a substitute for legal or tax counsel. Any investment products or services named herein are for illustrative purposes only and should not be considered an offer to buy or sell, or an investment recommendation for, any specific security, strategy or investment product or service. Always consult a qualified professional or your own independent financial professional for personalized advice or investment recommendations tailored to your specific goals, individual situation, and risk tolerance. All examples are hypothetical and are for illustrative purposes only.
Information contained in the materials included is believed to be from reliable sources, but no representations or guarantees are made as to the accuracy or completeness of information. This document is provided for information purposes only and should not be considered as investment advice.
Dunham & Associates Investment Counsel, Inc. is a Registered Investment Adviser and Broker/Dealer. Member FINRA/SIPC. Advisory services and securities offered through Dunham & Associates Investment Counsel, Inc.