Salvatore M. Capizzi, CEPA, CBDA, is Dunham's Chief of Sales & Marketing and a 2026 Wealthies CMO of the Year Finalist. His work focuses on retirement planning, emerging trends for financial advisors, and advanced tax, trust, and estate strategies.
The wash sale rule does not currently apply to cryptocurrency. IRS Notice 2014-21 classifies crypto as property, not a security, so IRC Section 1091 — which blocks the tax-loss deduction if you buy back a "substantially identical" asset within 30 days — doesn't reach direct crypto trades, meaning you can sell Bitcoin at a loss and rebuy it immediately while still claiming the loss.
Update: A House committee advancedlegislation on September 16, 2026 that would close this loophole. Nothing has passed into law yet, so the exemption still holds for now.
Key Takeaways:
Cryptocurrency is not currently subject to the IRS wash-sale rule, creating a tax-loss harvesting opportunity that is not generally available with stocks or securities.
Crypto losses may be used to offset capital gains from stocks, funds, real estate, or other investments, even if the crypto is immediately repurchased.
Directly held crypto is treated differently from Bitcoin and Ethereum ETFs, which are securities and may be subject to wash-sale rules.
This planning window may not last, as lawmakers have repeatedly considered extending wash-sale rules to digital assets.
Advisors should coordinate with qualified tax professionals before implementing crypto tax-loss harvesting strategies for clients.
Does the Wash Sale Rule Apply to Cryptocurrency in 2026?
Tax loss harvesting crypto positions is one of the most overlooked year-round strategies available to clients who hold digital assets — and most advisors aren't talking about it.
With traditional portfolios showing strong gains over the past several years, opportunities for conventional tax-loss harvesting have become harder to find. When nearly everything is green, the harvest comes up empty.
But crypto markets are volatile by nature — and that volatility creates a recurring opportunity. When digital assets decline, clients can harvest those losses immediately and repurchase the same position. No 30-day waiting period. No substitute security required. (1)
And because cryptocurrency is not subject to the IRS wash sale rule, clients can realize losses and immediately repurchase the same crypto position - a tax planning benefit unavailable in traditional securities.
For example, if a client buys Bitcoin at $100,000 and it drops to $70,000 - that is an unrealized $30,000 loss. Under current IRS rules, they can at $70,000, lock in the $30,000 capital loss for tax purposes, and immediately buy back the same amount of Bitcoin. Their crypto position is essentially unchanged, but the $30,000 loss can now offset stock gains or up to $3,000 of ordinary income, with any unused amount carried forward.
For clients who own Bitcoin or other digital assets, this market correction may present a valuable tax planning opportunity that is not available in traditional securities.
Why the Wash Sale Rule Doesn't Apply to Crypto
Here is how you can add true value to clients who may own cryptocurrency.
The IRS currently treats cryptocurrency as property rather than a security. Because the wash sale rule applies specifically to securities and stocks, it does not apply to cryptocurrency transactions. (2)
This could create an attractive planning opportunity.
Your clients who own Bitcoin, Ethereum, or other cryptocurrencies can:
Sell the asset at a loss
Immediately repurchase the same crypto (no 30-day wash sale restriction)
Still claim the full tax loss under current IRS rules
Use the loss to offset capital gains from other investments
Reduce up to $3,000 of ordinary income per year
Carry forward unused losses indefinitely
That is the advantage crypto offers that stocks do not.
Which Crypto Assets Qualify — and Which Don't
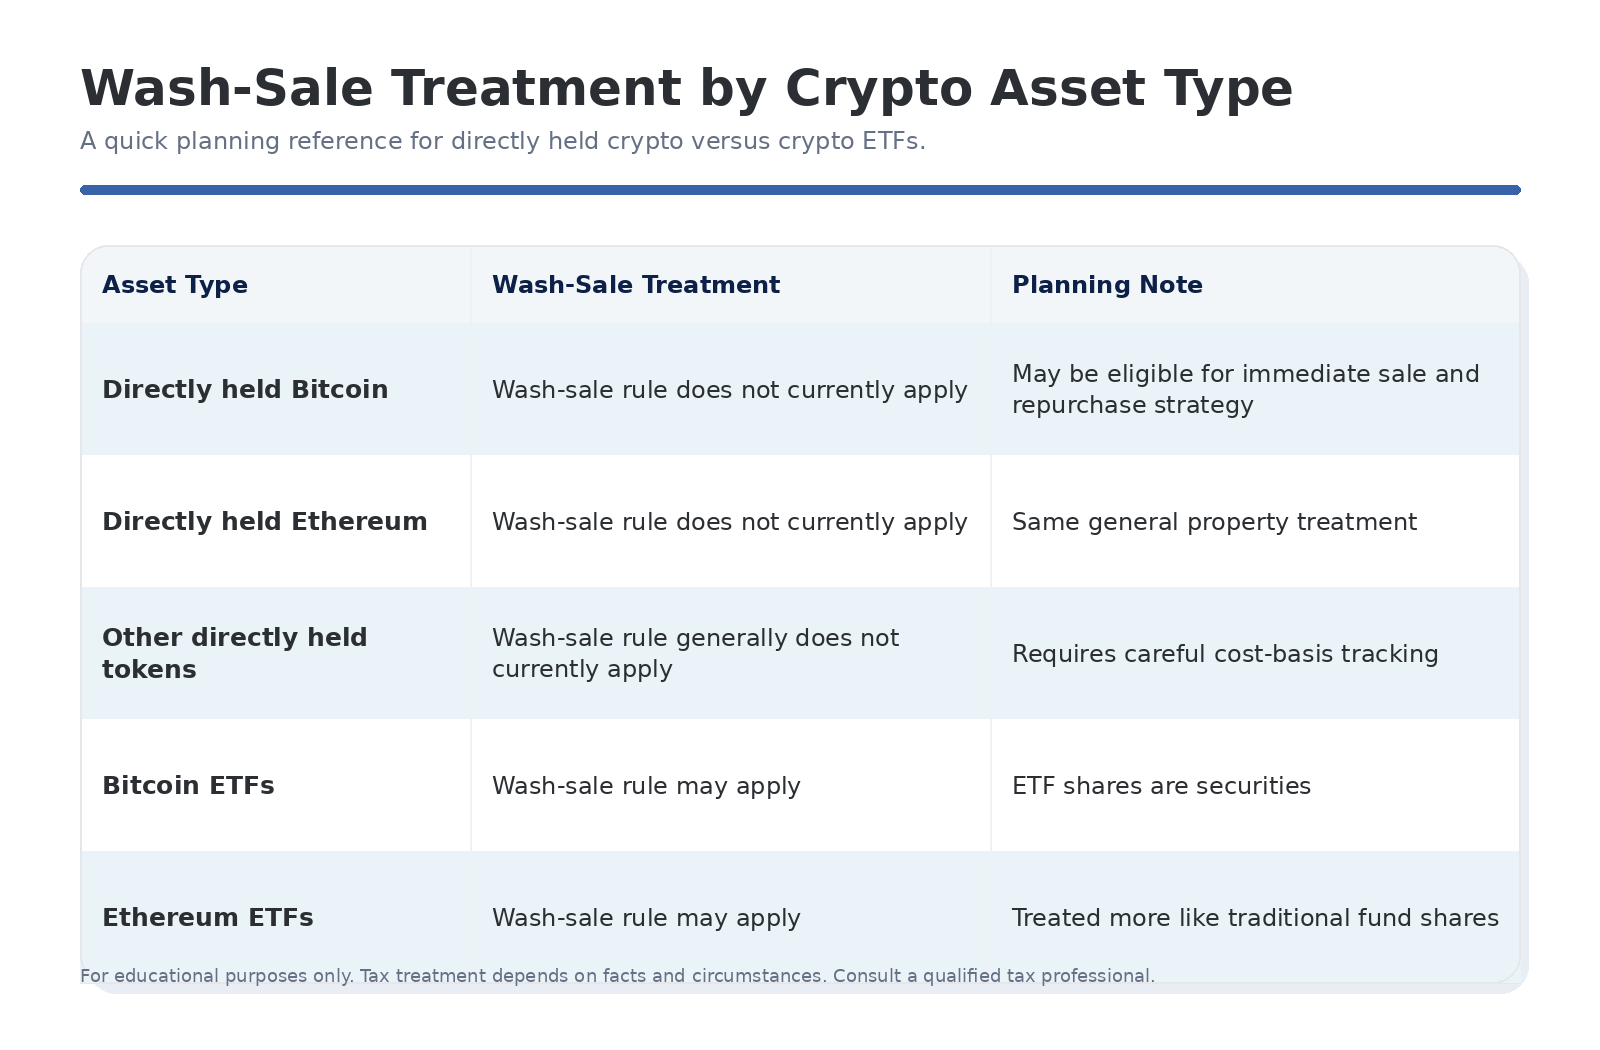
The absence of wash sale rule applies broadly across the cryptocurrency universe. Here is how it works for different types of digital assets: (3)
Decentralized finance (DeFi) tokens and governance tokens from Decentralized Autonomous Organizations (DAOs) also fall under this property classification. If your client has losses in protocols like Uniswap, Aave, or other DeFi platforms, those losses can be harvested without any current wash sale restrictions.
NFTs
Non-fungible tokens (NFT) represent another category of digital property. While the market for NFTs has been particularly volatile, losses in these assets can currently be realized and claimed without triggering wash sale rules.
Blockchain and Cryptocurrency ETFs
Bitcoin and Ethereum exchange-traded funds that trade on traditional stock exchanges are subject to the wash sale rule. These ETFs are structured as securities that trade like stocks, even though they hold cryptocurrency as their underlying asset. These ETFs are securities, and the wash sale rule applies.
Important Tax Caveats and the Changing Legal Landscape
While this strategy is currently permitted under existing tax law, the regulatory environment surrounding cryptocurrency taxation is evolving rapidly. Several factors require careful consideration before implementing this approach with clients.(3)
Legislative Proposals Are Ongoing
Multiple bills introduced in Congress since 2021 have sought to apply the wash sale rule to digital assets. I consider this a clear regulatory intent to close what lawmakers view as a tax loophole.
The Direction Is Clear
Tax policy experts and industry observers widely expect that wash sale rules will eventually apply to cryptocurrencies. Many tax policy observers expect wash-sale rules may eventually be extended to digital assets, though timing and final legislative language remain uncertain.
Retroactive Application Risk
While most tax professionals believe that any new legislation would apply prospectively rather than retroactively, there is no guarantee. In rare circumstances, Congress has applied tax law changes retroactively. Clients should understand that, while unlikely, there exists a theoretical risk that future legislation could invalidate previously claimed losses.
Economic Substance Doctrine
A broader tax principle exists, known as the economic substance doctrine, which requires that transactions have a genuine economic purpose beyond mere tax avoidance. While selling and immediately repurchasing cryptocurrency does not currently violate wash sale rules, transactions that appear to have no purpose other than generating tax losses could be challenged on other grounds.
The Role of Tax Professionals
Given the complexity and evolving nature of cryptocurrency taxation, clients must consult with qualified tax professionals before implementing any tax loss harvesting strategy.
A few specific considerations:
Risk tolerance varies. Conservative clients may prefer to avoid the strategy due to regulatory uncertainty. A tax advisor can calibrate the approach accordingly.
State tax treatment varies significantly. Some states follow federal rules; others have specific provisions for digital assets. Multi-state situations require professional analysis.
This is not a DIY strategy. The IRS guidance on digital assets continues to evolve, and errors in cost basis tracking or transaction reporting can create significant problems.
Tools to Help Track Crypto Transactions
One of the biggest practical challenges is tracking transactions across multiple wallets, exchanges, and platforms. Several professional-grade tools exist to help advisors and clients manage this.
The platforms below are among the most widely used - advisors and clients should conduct their own due diligence:
CoinLedger
CoinTracker
Koinly
ZenLedger
TokenTax
These platforms connect exchange accounts via API keys or CSV imports, automatically calculate cost basis, track holding periods, and generate comprehensive tax reports. Most support FIFO, LIFO, or specific identification methods to maximize tax benefit - and many integrate directly with popular tax preparation software.
Closing thoughts
The combination of strong equity performance and crypto volatility creates a recurring planning opportunity - one that exists regardless of the time of year. When traditional portfolios are green but clients' digital assets are in the red, strategic crypto tax loss harvesting can offset those capital gains without triggering wash sale restrictions.
Unlike traditional tax-loss harvesting - which is often compressed into year-end - the absence of a wash sale restriction means this strategy can be executed any time the market presents a meaningful decline.
The window exists now. But it likely won't be open forever.
Frequently Asked Questions About Crypto Tax-Loss Harvesting
Does the wash-sale rule apply to cryptocurrency? No, not currently. The IRS treats cryptocurrency as property rather than a security, and the wash-sale rule only applies to securities and stocks. That means investors can sell crypto at a loss and immediately buy it back without waiting 30 days, something not allowed with stocks. This treatment could change if Congress or the IRS updates digital asset rules.
Can I sell crypto at a loss and buy it back right away? Yes, under current IRS rules. Because crypto counts as property, not a security, there's no 30-day waiting period or substitute-asset requirement like with stocks. You can sell at a loss, lock in that capital loss for tax purposes, and buy back the same amount right away, keeping your position basically unchanged while claiming the loss.
Do Bitcoin and Ethereum ETFs get the same tax treatment as direct crypto holdings? No. Bitcoin and Ethereum ETFs trade on stock exchanges and are structured as securities, so they fall under the wash-sale rule even though they hold crypto as the underlying asset. Direct holdings of Bitcoin, Ethereum, or other tokens in wallets or exchanges don't face that restriction, since the IRS still classifies them as property.
Could the wash-sale rule be extended to crypto in the future? It's possible. Lawmakers have introduced multiple bills since 2021 to extend wash-sale rules to digital assets, and many tax policy observers expect this to happen eventually. Timing and final language remain uncertain, and while most experts think new rules would apply going forward rather than retroactively, there's no guarantee. Talk with a tax professional before relying on this strategy long term.
Do DeFi tokens and NFTs qualify for this tax-loss harvesting strategy too? DeFi tokens, DAO governance tokens, and NFTs all currently qualify, since the IRS treats them as property just like Bitcoin or Ethereum. Losses in protocols such as Uniswap or Aave, or in NFT holdings, can be harvested and repurchased right away without triggering wash-sale restrictions. This differs from Bitcoin and Ethereum ETFs, which are securities and remain subject to the rule.
Internal Revenue Service — Frequently Asked Questions on Virtual Currency Transactions [irs.gov]
Internal Revenue Service — Frequently Asked Questions on Digital Asset Transactions[irs.gov]
Internal Revenue Service — Notice 2014-21: IRS Virtual Currency Guidance[irs.gov]
Internal Revenue Service — Notice 2023-34: Modification of Notice 2014-21 [irs.gov]
GovInfo — 26 U.S.C. Section 1091: Loss from Wash Sales of Stock or Securities [govinfo.gov]
Cornell Law School — 26 CFR Section 1.1091-1: Losses from Wash Sales of Stock or Securities[law.cornell.edu]
Internal Revenue Service — Publication 544: Sales and Other Dispositions of Assets [irs.gov]
Internal Revenue Service — Topic No. 409: Capital Gains and Losses [irs.gov]
Taxpayer Advocate Service — When Can You Deduct Digital Asset Investment Losses?[taxpayeradvocate.irs.gov]
DLA Piper — Proposed Legislation Would Subject Cryptocurrency to Tax Rules for Wash Sales[dlapiper.com]
Thomson Reuters — Congress Is Finally Taxing Crypto-Assets: Here’s What Your Tax Clients Need to Know[thomsonreuters.com]
Disclosures:
This communication is general in nature and provided for educational and informational purposes only. It should not be considered or relied upon as legal, tax or investment advice or an investment recommendation, or as a substitute for legal or tax counsel. Any investment products or services named herein are for illustrative purposes only and should not be considered an offer to buy or sell, or an investment recommendation for, any specific security, strategy or investment product or service. Always consult a qualified professional or your own independent financial professional for personalized advice or investment recommendations tailored to your specific goals, individual situation, and risk tolerance. All examples are hypothetical and are for illustrative purposes only.
Federal and state laws and regulations are complex and subject to change, which can materially impact your results.
IRS Circular 230 Disclosure: To ensure compliance with requirements imposed by the IRS, we inform you that any U.S. federal tax advice contained in this communication (including any attachments) is not intended or written to be used, and cannot be used, for the purpose of (i) avoiding penalties under the Internal revenue Code or (ii) promoting, marketing or recommending to another party any transaction or matter addressed herein. Information contained in the materials included is believed to be from reliable sources, but no representations or guarantees are made as to the accuracy or completeness of information. This document is provided for information purposes only and should not be considered as investment advice.
Dunham & Associates Investment Counsel, Inc. is a Registered Investment Adviser and Broker/Dealer. Member FINRA/SIPC. Advisory services and securities offered through Dunham & Associates Investment Counsel, Inc.