Content Editor, Dunham | 2025 ThinkAdvisor Luminary Award Winner | 2026 Wealthies Finalist — Thought Leader of the Year | Macroeconomics, markets, geopolitics & global trends
Originally published May 2025 | Author Update August 2025:
China’s electric-vehicle price war reflects intense competition, high factory capacity, and weaker domestic demand in parts of the auto market. BYD’s price cuts may help consumers, but they also pressure automaker margins, suppliers, and rivals. The broader effect could include more Chinese vehicle exports, trade restrictions, and pressure on global manufacturers.
Key Takeaways
BYD slashed EV prices by up to 34%, triggering a nationwide auto price war in China.
The fallout is collapsing margins, rising supplier stress, and inflated sales practices.
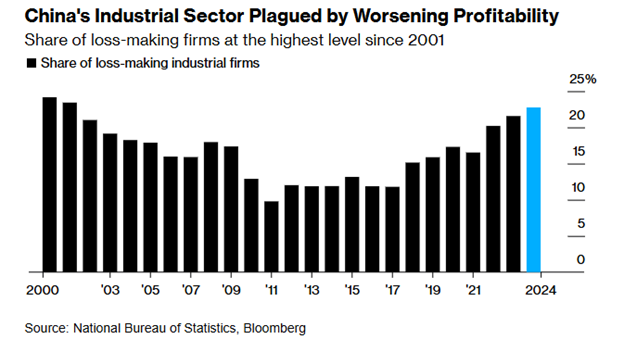
Nearly 25% of China’s industrial firms are now unprofitable - the highest since 2001.
Local governments are propping up “zombie firms,” worsening industrial overcapacity.
Ultra-cheap Chinese goods, including autos, are flooding global markets.
Countries from India to Russia are responding with tariffs and trade crackdowns.
China’s auto sector crisis reflects deeper economic instability with global consequences.
Put simply, when one automaker cuts prices to gain market share, the others must follow - or lose ground. Company A cuts 10%, Company B cuts 11%, Company C cuts 12%, and so on.
But this isn’t just about discounts - it’s about the ripple effects.
Suppliers are worried about missed payments from auto giants.
Beijing officials are worried the price war could spiral into chaos.
Investors are worried about margins vanishing and accounting gimmicks.
Foreign firms and governments are worried as prices sink and exports surge.
Still, this isn’t just an auto story.
It’s a symptom of something much deeper.
China’s private industrial base is running dangerously lean. Unprofitable firms now sit at multi-decade highs. And the auto price war is pouring fuel on that fire - with consequences that won’t stay contained within China’s borders.
Let me show you why in this exclusiveedition of the Morning Pour.
China’s car market is flashing red on multiple fronts – such as:
Overcapacity
Margins collapsing
Ballooning inventory
Creative accounting that raises eyebrows
And while these issues aren’t new, they’ve amplified in the past few weeks.
To give you some context: in late May, BYD slashed prices on 22 models - some by over 30%. Such an aggressive move was designed to undercut rivals and offload excess inventory, but it exposed the deeper strain in China’s overheated EV space as a flood of new entrants and repeated price cuts have gutted margins so badly that Beijing stepped in.
Chinese officials summoned top auto executives and urged them to “self-regulate” - aka stop selling below cost and don’t drag the entire industry down.
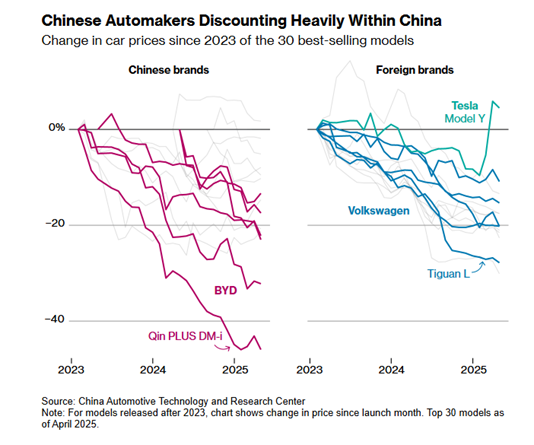
Such steep price cuts - between 15% to 50% - are gutting profits across the board.
Same costs + lower prices = collapsing margins.
And it’s not just domestic players. To stay in the race, foreign brands like Volkswagen and Mercedes have been forced to follow suit just to compete in China - making it an international issue.
Figure 1: Bloomberg, June 2025
And since BYD’s May 23 price-slashing announcement – its stock is down about ~20% as of writing this.
But it’s not just shareholders that are nervous. Suppliers are anxious too.
Well, for companies like BYD, this is a big change because historically, their payment cycles stretched well beyond 100 days (sometimes the wait is over half a year).
In 2023, BYD took an average of 275 days to pay suppliers. That’s not just slow - it’s absurd.
You might ask, “Suppliers wait nearly a year to get paid? How?”
Simple. Debt.
In China’s auto industry, many suppliers are paid with promissory notes instead of cash. BYD’s DiLian platform lets them trade or cash these early - for a fee. And as of May 2023, BYD had issued over 400 billion yuan ($56B) of these IOUs - using them as collateral (the latest data available).
Some suppliers - usually the larger ones - make it work. They borrow against what they’re owed (aka they use the note as collateral).
But in today’s EV price war, delayed payments aren’t harmless. Margins are already thin. Cash is tight. And just one missed note payment can ripple fast - wages go unpaid, inventory stalls, and debt piles up.
And that’s the real risk here. These notes only hold if the automaker pays. If not, it’s not just a delay - it’s a chain reaction.
This system chokes supplier cash flow and magnifies stress across the supply chain.
So, while the 60-day pledge is a step in the right direction, for many, it’s still wait-and-see as competition heats up.
The Debt Nobody Wants to Talk About
Now comes the bigger risk - the one that may be hiding in plain sight.
Worse, no one really knows who’s owed, when payments are due, or what the terms are. As GMT puts it, “The nature of these obligations is unclear.”
The point is, BYD - and likely others - may be running on borrowed money and borrowed time. They're pushing for market share while quietly stretching themselves thin.
And if suppliers are already waiting close to a year for payment and they're issuing IOUs left and right, you have to wonder:how close to the edge are they already?
Zero-Mileage Cars: Inflated Sales, Hidden Risks?
Meanwhile, there’s the growing issue of “zero-mileage cars” – which is another symptom of the auto price war and one that Beijing has directly said needs to stop4.
“What are zero-mileage cars?” These are brand-new vehicles that haven’t been sold to real customers, but still show up as “sold” on paper. Dealers register them to themselves or affiliated entities so automakers can hit sales targets. It’s like moving inventory from one garage to another and calling it a sale - while pocketing a government subsidy.
Here’s how it works: Automakers - eager to hit quotas and make a sale - “sell” cars to friendly dealerships or partner firms. Once registered, the vehicles count toward official sales and receive a government subsidy. But instead of ending up with real buyers, they’re quietly moved to the used car market - usually at steep discounts. Now, it may look like a win-win: automakers boost their numbers, dealers flip inventory, and consumers get cheap EVs. But regulators are catching on – with many now seeing it as subsidy abuse as public funds are claimed for what’s essentially a fake sale.
And as I wrote to you previously, it’s not just a gimmick. It’s inventory laundering – a way that masks weak demand and props up balance sheets.
But such gimmicks distort sales figures, mislead investors, and fuel a vicious feedback loop.
Fake sales justify real production > oversupply deepens > prices fall further > repeat.
Remember, you can put lipstick on a pig - but it's still a pig.
Faced with this, debt-ridden local governments are offering tax breaks and subsidies to keep firms alive and prevent mass layoffs and revenue loss.
But here’s the real problem. . .
Propping up unprofitable firms only worsensChina’s overproduction crisis.
Put simply, Beijing’s stuck between a rock and hard place: let unprofitable firms fail and trigger mass unemployment, or keep them afloat with government money and worsen the supply glut that’s already rattling global markets
Thus, for a party built on the promise of “social stability,” the choice is obvious: subsidize to survive – which means too many goods pile up, prices drop, and companies feel the pain.
These are infamously known as “zombie firms” – aka businesses that would fail without constant state aid or credit.
And these zombies are growing in number, flooding markets with products few want, dragging down profits across entire sectors.
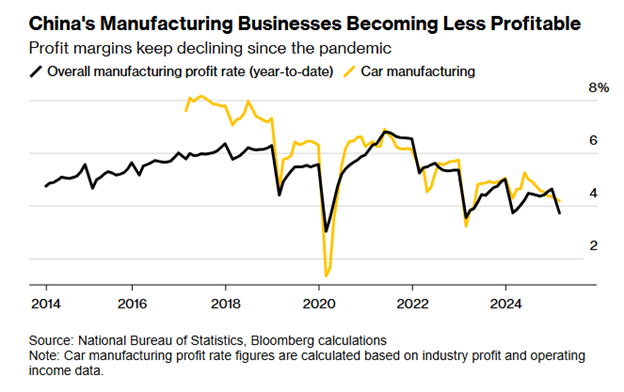
Just look at the chart below - it shows collapsing manufacturing profits, especially for car producers.
Figure 3: Bloomberg, June 2025
I expect Beijing to continue subsidizing these firms – keeping jobs and growth from falling off a cliff and sparking public unrest (which the Chinese Communist Party is worried about).
But here’s the problem with that. . .
In this hyper-globalized world, domestic policies can directlyinfluence global trade.
So, this isn’t just a story about car prices in the end – but rather it’s about a fragile situation spilling over into global markets. . .
The Global Ripple Effect: From Tariffs to Trade Tensions
“Wait, why does China’s auto-price war and over-subsidized manufacturing affect the world?”
China’s economy has been producing far more than its consumers are willing - or able - to buy. This mismatch between weak domestic consumption and excess production creates pressure to offload goods elsewhere (aka find buyers abroad).
Why? Because if they can’t find buyers at home = businesses can’t make money = can’t pay employees = can’t spend themselves = and repeat the cycle.
It looks like the mainstream economic media is finally catching on to this. As the New York Times6 recently did a piece on this, noting: “The flood of exports from China is the consequence of government policy and a slowing domestic economy. To soften the blow of a real estate crisis that reduced the wealth of millions of households, Beijing has for several years been shoveling money into its manufacturing sectors, which are making far more things than there is demand for at home.”
Thus, Chinese companies - especially in sectors like electric vehicles, solar panels, and steel - push their excess into global markets at ultra-low prices – making it their problem.
This then floods international markets, negatively hurting local producers in other countries who can’t compete with the artificially cheap exports.
Put simply, China’s internal imbalance doesn’t stay confined - it spills over by reshaping supply chains, pricing dynamics, and even the politics of global trade.
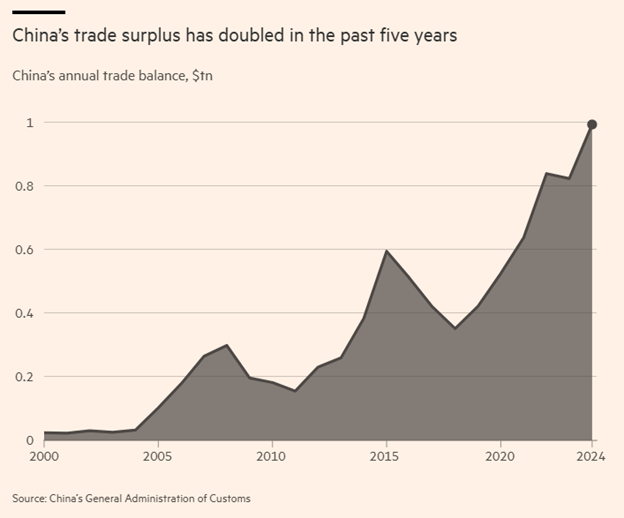
No other point shows this like China’s annual trade balance – which hit a record high ~$1 trillion last year – which is synonymous with saying they sold more than $1 trillion than they bought globally).
And while China running a surplus isn’t exactly “new” (they’ve done it for over three decades) - the gap between its exports and imports has more than doubled since 2019, indicating that China’s doubled down on their on their aggressive “Sell more, buy less” strategy.
India and Brazil are probing the Chinese dumping of metal, chemicals, and tires.
Mexico’s president blames cheap Chinese goods for gutting textiles and shoes and will review tariffs against China.
Indonesia fears job losses in its textile sector from a flood of low-cost Chinese imports.
Even Russia slapped tariffs on Chinese cars after they captured two-thirds of its market.
This is why China’s auto market matters - it’s not isolated.
There are two big reasons for this:
First, China’s automakers are slashing prices so aggressively that foreign brands like Toyota and Mercedes are losing ground in China - resulting in fewer sales and shrinking market share.
Then, that same excess inventory floods global markets, undercutting those brands on their home turf - leading to falling profits, factory closures, and lost jobs around the world.
It’s a one-two punch. And this price war is just another bullet in the chamber of the global trade war.
What to Watch Next
Several developments could determine whether the price war fades or becomes more damaging:
Domestic demand: Stronger Chinese household consumption could absorb more vehicle output.
Industry consolidation: Weaker automakers may reduce production, merge, or leave certain segments.
Profitability: Watch margins and cash flow, not just delivery volumes.
Supplier conditions: Timely payments and stable financing would reduce supply-chain stress.
Export growth: Faster exports can relieve domestic inventory pressure but may intensify trade disputes.
Policy response: Tariffs, subsidies, trade investigations, and regulatory changes can alter market conditions quickly.
Final Thoughts: Why This Auto Crisis Is Just the Beginning
What we’re seeing isn’t just a price war - it’s a pressure valve for deeper economic stress. Pressure’s been building for years, and now it’s trying to escape. But without a proper release, something’s bound to blow.
China’s automakers aren’t slashing prices from a place of strength. They’re doing it out of desperation to move excess inventory.
And behind the falling sticker prices are delayed payments, inflated sales, overcapacity, and mounting debt. Add in state-backed zombie firms and a bloated industrial sector, and you’ve got a system creaking at the seams.
And because China exports that excess via ultra-cheap goods, the rest of the world feels it.
This isn’t a localized slowdown. It’s a ripple turning into a global wave.
Most headlines stop at cheap car prices. But if you look beneath the hood, It’s a fragile economy trying to out-export its way out of a slowdown - one bargain at a time.
So, keep your eyes on China’s auto sector. This isn’t over.
As always, just some food for thought.
FAQ:
Why did BYD cut EV prices in China? BYD reduced prices on selected models during 2025-26 amid intense competition in China’s EV market. Automakers use price cuts to defend market share, reduce inventory, and attract buyers, but the strategy can reduce profit margins.
Is China’s EV price war bad for consumers? Lower prices can make EVs more accessible and increase consumer choice. The longer-term effect depends on whether price competition remains financially sustainable for automakers, dealers, and suppliers.
What are zero-mileage used cars in China? Zero-mileage used cars are newly registered vehicles that are later sold as used cars despite having little or no driving history. Chinese authorities have raised concerns that the practice may affect market transparency, sales reporting, and consumer protection.
How can China’s EV price war affect other countries? Chinese automakers may seek more sales overseas when domestic competition is intense. Lower-priced imports can benefit consumers but may also pressure local producers and increase the chance of tariffs, trade investigations, or other restrictions.
What should investors monitor? Investors should watch vehicle pricing, margins, inventory, supplier-payment practices, export growth, trade-policy developments, and China’s domestic consumer demand. These factors can affect automakers, suppliers, commodities, and trade-sensitive industries.
This communication is general in nature and provided for educational and informational purposes only. It should not be considered or relied upon as legal, tax or investment advice or an investment recommendation, or as a substitute for legal or tax counsel. Any investment products or services named herein are for illustrative purposes only and should not be considered an offer to buy or sell, or an investment recommendation for, any specific security, strategy or investment product or service. Always consult a qualified professional or your own independent financial professional for personalized advice or investment recommendations tailored to your specific goals, individual situation, and risk tolerance. All examples are hypothetical and are for illustrative purposes only.
Information contained in the materials included is believed to be from reliable sources, but no representations or guarantees are made as to the accuracy or completeness of information. This document is provided for information purposes only and should not be considered as investment advice.
Dunham & Associates Investment Counsel, Inc. is a Registered Investment Adviser and Broker/Dealer. Member FINRA/SIPC. Advisory services and securities offered through Dunham & Associates Investment Counsel, Inc.